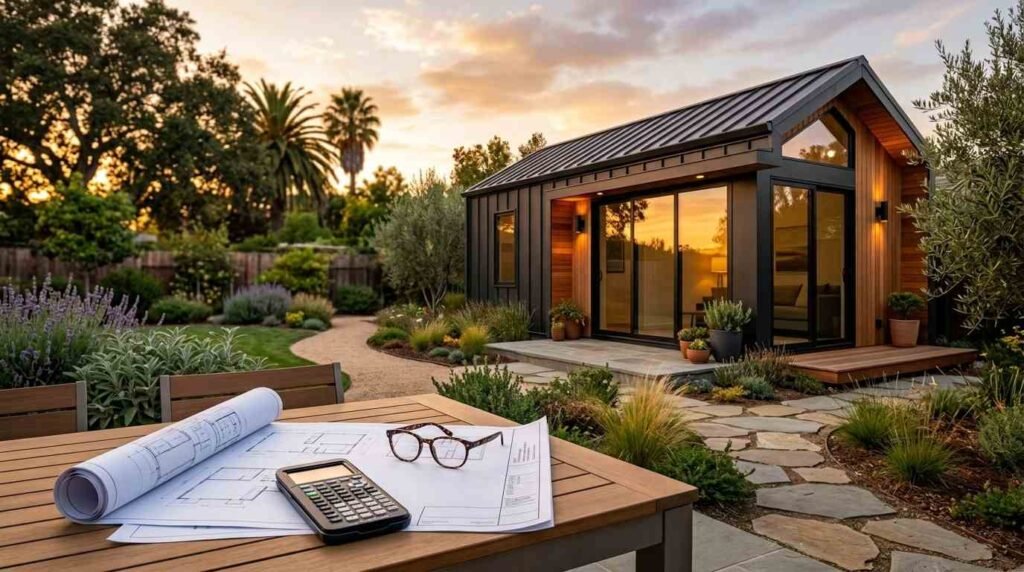
An accessory dwelling unit is a legal second home built on a single-family lot, and financing one works differently than financing your primary house. Most homeowners in California pay for an ADU using home equity, a construction loan, or a combination of both, because ADUs rarely qualify for standard mortgage products on their own.
I’ve watched too many homeowners fall in love with a floor plan before they understand how they’re actually going to pay for it. That gap between excitement and financial reality is where projects stall out or get built with the wrong insurance in place.
I cover the full range of financing tools available for ADU construction in California, from home equity and cash-out refinancing to construction loans and state-backed programs, how lenders evaluate these applications, and what proper insurance coverage looks like before and after your ADU is finished.
How ADU Financing Works in California
Financing an ADU isn’t the same process as buying a house. A lender is not evaluating a finished, appraised property. They’re evaluating a construction project that doesn’t exist yet, on a lot that already has a mortgage.
That’s the core tension in every ADU loan conversation. And it’s why so many homeowners get steered toward home equity first: the value already sitting in your primary residence is the collateral that makes the project financeable.
California has pushed hard to make ADUs easier to build, loosening zoning restrictions and permitting timelines across most municipalities. California’s Department of Housing and Community Development reports that ADU permits statewide have grown significantly since 2020 reforms took effect. But financing hasn’t caught up as fast as the zoning has.
Why ADUs Require a Different Financing Approach Than Primary Homes
An ADU is a structure with no sales history on its own. Appraisers value it based on comparable ADU sales in your area, and in many California markets, those comparables are still thin.
That thinness matters because it limits how much a lender will lend against the ADU’s projected value alone. Most financing structures work around this by leaning on the equity you’ve already built in the primary home instead.
Home Equity Loans and HELOCs for ADU Construction
A home equity line of credit lets you borrow against the equity in your existing house and draw funds as construction costs come in. I like HELOCs for ADU projects because you’re not paying interest on money you haven’t spent yet.
You get a credit line, a draw period, and a repayment period. During construction, you pull funds as the contractor invoices land, and you only owe interest on the amount actually drawn.
A home equity loan works differently; it’s a lump sum, fixed rate, fixed term. That structure suits homeowners with a locked-in budget and a fixed-price construction contract, where cost overruns are less of a wildcard.
How Much Equity You Need to Qualify
Lenders generally cap combined loan-to-value around 80 to 85 percent of your home’s current appraised value. That number includes your existing mortgage balance plus the new HELOC or equity loan combined.
A home worth $900,000 with a $400,000 mortgage balance leaves meaningful room under an 80% CLTV cap often enough to fund a full ADU build. A home closer to its equity ceiling has far less room to work with, and that math needs to happen before you fall in love with floor plans.
Cash-Out Refinancing for ADU Projects
Cash-out refinancing replaces your existing mortgage with a new, larger one and hands you the difference in cash. It makes sense when current mortgage rates sit at or below your existing rate, because you’re not sacrificing a good rate to access the equity.
The math gets uglier fast when your existing rate is meaningfully lower than today’s rates. Refinancing the entire mortgage balance at a higher rate to access a relatively small amount of ADU cash often costs more over the loan’s life than a separate HELOC would.
When a Cash-Out Refi Makes More Sense Than a HELOC
A cash-out refi wins when you’re already planning to refinance for other reasons, current rates are favorable, or you want one single fixed monthly payment instead of juggling a primary mortgage and a second lien. It also simplifies things if you’re not confident managing a draw schedule.
A HELOC wins when your existing mortgage rate is excellent, and you don’t want to touch it. Keep the two purposes separate, and the decision gets much clearer.
Construction Loans and Renovation Loans for ADUs
A construction loan is built specifically for projects that don’t exist yet. The lender disburses funds in stages tied to construction milestones, not all at once, and the loan typically converts to permanent financing once the ADU is complete.
Renovation loan products, including those tied to a first mortgage refinance, bundle the purchase or refinance of the primary home with the ADU construction costs into a single loan. These work well for buyers purchasing a property specifically with ADU plans already in mind.
Construction-to-permanent loans require more documentation upfront than a straightforward HELOC. Lenders want architectural plans, a licensed contractor, a fixed-price contract, and a realistic construction timeline before they release the first draw.
How Draw Schedules Work During Construction
Lenders release funds in stages, and each stage typically requires a site inspection confirming the work matches the draw request. A rough framing draw won’t release until framing is actually standing.
Delays between draws are the single biggest cause of frustration on construction loan projects. Working with a contractor who understands draw schedules and inspection timing keeps the project and your cash flow moving.
California-Specific ADU Loan Programs and State Incentives
California has rolled out several programs aimed specifically at ADU affordability, recognizing that financing gaps were slowing adoption of a housing type the state actively wants more of. CalHFA’s ADU Grant Program provides up to $40,000 toward pre-development costs like permits, architectural fees, and site prep for eligible low- to moderate-income homeowners.
That grant doesn’t cover actual construction costs, which trips people up. It’s designed to remove the upfront barrier of permitting and design fees that stop many projects before ground ever breaks.
Some regional housing finance agencies and local municipalities layer additional incentives on top, including reduced permitting fees or expedited plan review for ADUs meeting specific affordability or accessibility criteria.
CalHFA ADU Grant Program Eligibility
Eligibility ties to household income relative to the area median income where the property sits, and the homeowner must occupy the primary residence on the lot. Funds get reimbursed after the homeowner has already paid the qualifying pre-development costs, not disbursed upfront.
That reimbursement structure means you still need some capital available before the grant money lands. It’s a meaningful offset, not a full financing solution on its own.
Personal Loans and Alternative Financing Options
Personal loans work for smaller ADU projects, particularly prefab or modular units with lower total costs. They skip the appraisal and equity requirements entirely, which speeds up approval considerably.
The tradeoff is cost. Interest rates on unsecured personal loans run well above home equity products, and loan amounts typically cap out lower than what a full-size ADU build requires.
Some homeowners combine financing sources: a personal loan or savings for site prep and permits, then a construction loan or HELOC for the build itself. Layering sources adds complexity but can bridge a genuine funding gap.
When a Personal Loan Fits a Small ADU Budget
A personal loan makes the most sense for detached prefab units under roughly $100,000, where the loan amount fits within typical unsecured lending limits. It also suits homeowners who don’t have enough home equity yet to qualify for equity-based products.
Beyond that price point, the interest cost differential against secured financing usually outweighs the speed and simplicity benefits.
How Lenders Evaluate ADU Loan Applications
Lenders look at three things closely: your existing debt-to-income ratio, the appraised value of the completed project, and your overall creditworthiness. An ADU application adds a layer that most standard mortgage underwriting doesn’t typically handle: projected rental income from the future unit.
Some lenders count a percentage of projected ADU rental income toward your qualifying income, which can meaningfully improve your DTI ratio. Not every lender does this, and the ones that do require specific documentation, like a market rent analysis from a licensed appraiser.
Debt-to-Income and Appraisal Considerations for ADUs
Most lenders want your total debt-to-income ratio at or below 43 to 45 percent after the new financing is factored in. The ADU’s projected completed value gets weighed against comparable ADU sales, which remain limited in many California submarkets.
That comparable scarcity means appraisals on ADU projects run more conservatively than homeowners often expect. Building in a buffer between your projected appraisal and your actual budget protects against this gap.
Insuring Your ADU During and After Construction
Insurance for an ADU splits into two distinct phases, and treating them as one thing is a mistake I see constantly. During construction, the structure needs builder’s risk coverage. Once it’s finished and occupied, it needs to be added to your standing homeowners policy.
Skipping builder’s risk coverage during construction leaves an unfinished structure completely uninsured against fire, storm damage, theft, and vandalism. A standard homeowners policy generally does not extend coverage to a structure under active construction.
Builder’s Risk Insurance vs. Homeowners Policy Coverage
Builder’s risk insurance is a policy that covers a structure specifically during the construction phase, protecting materials, labor, and the partially built structure against covered perils. It’s typically purchased by either the homeowner or the general contractor, and the contract should specify who carries it.
A homeowners policy covers a completed, occupied structure against similar perils but explicitly excludes structures mid-construction in most cases. The transition between these two coverage types needs to happen the moment the ADU passes final inspection, not weeks later.
Updating Homeowners Insurance Once the ADU Is Built
Once your ADU passes final inspection, it needs to be added to your homeowners policy immediately. This isn’t automatic. Insurers don’t know your square footage changed unless you tell them.
Adding square footage and a second dwelling unit to your property increases your home’s total rebuild cost estimate, which directly affects your dwelling coverage limit. Underinsuring at this stage is common, and it’s expensive to discover after a loss.
How an ADU Affects Your Premium and Rebuild Cost Estimate
Your premium increases to reflect the added rebuild cost of the new structure, plus any additional liability exposure if you’re renting the unit out. The National Association of Insurance Commissioners notes that dwelling coverage should reflect full replacement cost, not market value, since rebuild costs and market prices move independently.
If the ADU will generate rental income, standard homeowners policies typically require a landlord endorsement or a separate rental dwelling policy to cover liability tied to a tenant-occupied structure. Skipping this step is one of the most common and costly oversights I see after an ADU is completed.
Common Financing and Insurance Mistakes to Avoid
The most expensive mistakes on ADU projects almost never happen during construction. They happen in the paperwork before and after the financing structure is chosen without fully understanding the terms, or the insurance update that never got made.
Underestimating total project cost when securing financing leaves homeowners scrambling mid-build for additional funds, often at worse terms than their original loan. Building a contingency buffer of 10 to 15 percent into your financing request from the start avoids that scramble entirely.
Underinsuring an ADU Built for Rental Income
A homeowner builds an ADU specifically to rent out, then forgets to notify their insurer once it’s occupied by a tenant. That gap leaves the homeowner exposed to liability claims a standard homeowners policy was never designed to cover.
Landlord endorsements and separate rental dwelling policies exist specifically for this scenario, and they typically cost far less than the exposure they eliminate.
Conclusion
Financing and insuring an ADU takes more coordination than a typical home project, spanning equity decisions, construction loan structures, and two distinct insurance phases. Getting the sequence right protects both your budget and your new structure.
California’s incentive programs and lending options continue to expand as ADU adoption grows statewide. Staying informed on financing terms and coverage requirements keeps your project protected from groundbreaking through move-in.
We build ADUs across California and guide homeowners through exactly these financing and insurance decisions every day. Reach out to Tiny Home Builders California to start planning your project with a team that understands both the construction and the numbers behind it.
Frequently Asked Questions
Can I use a HELOC to finance an ADU in California?
Yes, a HELOC is one of the most common ways homeowners finance ADU construction. You draw funds as needed during the build and pay interest only on the amount drawn.
How much does ADU insurance typically cost?
ADU insurance costs vary based on square footage, location, and whether the unit will be rented out. Adding an ADU generally increases your homeowners premium to reflect the higher total rebuild cost.
Do I need builder’s risk insurance for a small ADU?
Yes, builder’s risk insurance is needed for any ADU under active construction, regardless of size. Standard homeowners policies typically exclude structures that aren’t yet complete.
What credit score do I need for an ADU construction loan?
Most lenders want a credit score of at least 680 for ADU construction loans, though requirements vary by lender and loan type. Higher scores typically unlock better rates and terms.
Can projected rental income help me qualify for ADU financing?
Some lenders count a portion of projected ADU rental income toward your qualifying income. This requires a market rent analysis from a licensed appraiser and isn’t offered by every lender.
Is the CalHFA ADU Grant available to all California homeowners?
No, the CalHFA ADU Grant is limited to homeowners meeting specific income requirements relative to their area’s median income. The homeowner must also occupy the primary residence on the property.
What happens if I don’t update my homeowners insurance after building an ADU?
Your policy may not cover damage to the ADU or liability claims tied to it, since the insurer has no record of the added structure. This can result in high out-of-pocket costs after a covered loss.
Do cash-out refinances make sense if my current mortgage rate is low?
Generally no, since refinancing your entire mortgage balance at a higher rate to access ADU funds often costs more over time than keeping your current rate and using a separate HELOC.
Can I combine multiple financing sources for one ADU project?
Yes, many homeowners combine a personal loan or savings for pre-development costs with a construction loan or HELOC for the build itself. This layered approach can bridge funding gaps that a single loan product doesn’t cover.